How to Build a Pet Emergency Fund Without Raiding Savings

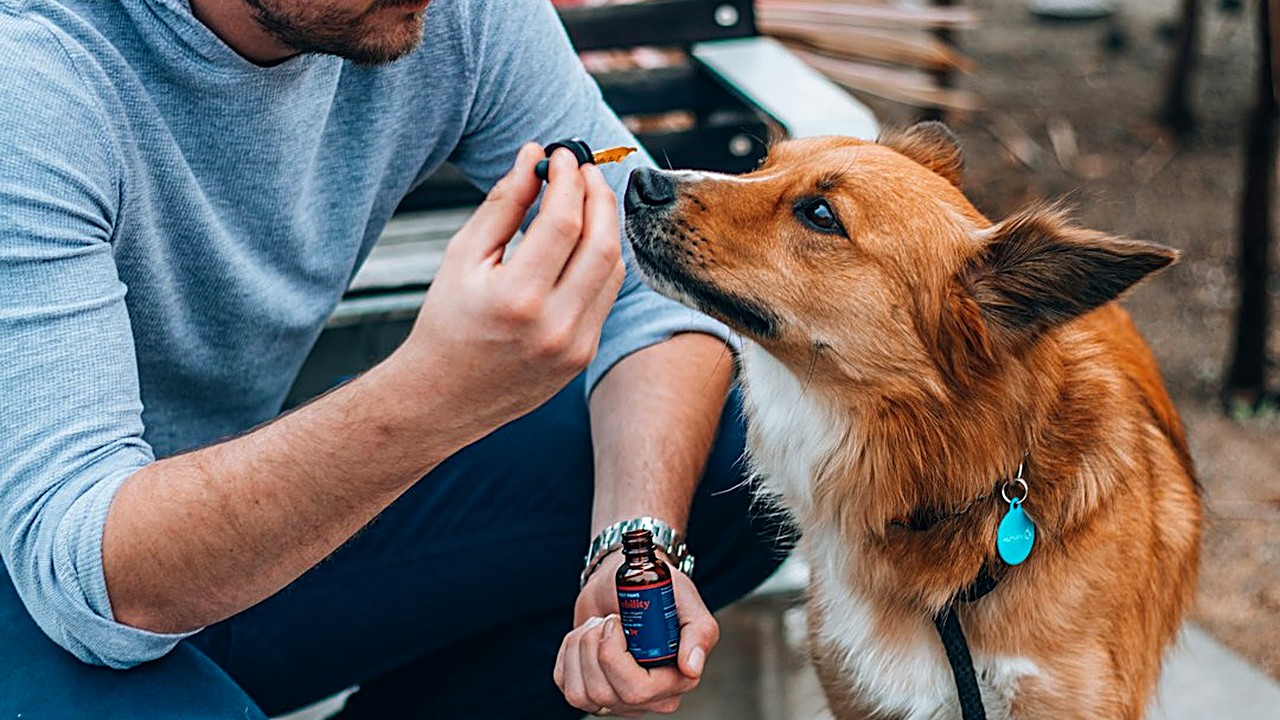
Quick answer: Build a separate pet emergency fund. Call your vet and the nearest emergency clinic for real prices, set a target, and move a fixed amount into a dedicated savings account every payday. Add a backup such as pet insurance or a vet payment plan.↗ Share on X
The best way to budget for pet emergencies without touching your main savings is to build a separate "pet fund" before anything goes wrong. Find out what an emergency visit costs at the clinic closest to you, set a target based on that number, and move a small fixed amount into a dedicated account every payday. Add a backup plan, such as pet insurance or a vet that accepts payment plans, so one bad night does not wipe out the money you saved for rent, car repairs or your own health.
That is the short answer. The rest of this article shows you how to do it step by step, even on a tight monthly budget.
Why should pet emergencies have their own fund?
 Stop the Big Tax Refund: Fix Your W-4 and Get Paid Monthly →
 Pet Budget Plan: Cover Vet Bills and Keep Saving Every Month →
 Cut $300 a Month Without Giving Up the Things You Love →
Your general emergency fund is meant for things like losing your job or a broken furnace. If your dog swallows a sock and needs surgery, and you pay for it from that same pot, two things happen:
1. Your safety net for big life problems gets smaller overnight.
2. You may feel guilty or stressed every time you think about refilling it.
A separate pet fund solves both problems. When the vet hands you an estimate, you already know which money is "allowed" to pay for it. You make the decision about your pet's care with a clearer head.
There is also a simple practical reason. Pet emergencies are not rare events over a pet's whole life. Most owners face at least a few surprise visits: an injury, a stomach problem, an allergic reaction, a bite from another animal. Treating these as "if" instead of "when" is what drains savings accounts.
Clear money tips in your inbox. No hype.
How much money should your pet fund hold?
Affiliate link. We may earn a commission on purchases, at no extra cost to you.
This content is informational and is not investment advice or financial consulting.
Do not guess. Get real numbers from the clinics you would actually use. Prices change a lot from one city to another, and between a regular vet and a 24-hour emergency hospital.
Here is a quick way to set your target:
1. Call your regular vet. Ask: "What does an urgent same-day exam cost?" Also ask what basic tests, like blood work or an X-ray, usually add.
2. Call the nearest 24-hour emergency hospital. Ask the price of the emergency exam fee alone. This fee is often higher than a normal visit, before any treatment.
3. Ask both clinics what a "typical" emergency bill looks like for your type of pet. Many front-desk staff will give you a rough range.
4. Write down the highest number you hear for a common emergency. That becomes your first target.
Then adjust for your situation using this table:
| Your situation | Suggested fund level |
|---|---|
| Young, healthy pet with insurance | Enough to cover your insurance deductible plus one emergency exam fee |
| Young, healthy pet without insurance | One full "typical emergency bill" from your calls |
| Senior pet, or a breed known for health issues | One to two typical emergency bills |
| More than one pet | Start with one bill, then add half a bill for each extra pet |
If the number feels huge, that is normal. You do not need to reach it this month. What matters is that you have a target and a plan to get there.
How do you find the money on a tight budget?
 How to Budget for Annual Expenses Using a Monthly Sinking Fund →
 How to Audit Your Cell Phone Plan to Cut Monthly Expenses Fast →
 New Job Budget: Survive the Gap Before Your First Paycheck →
You probably will not find a big lump sum. Instead, look for small amounts you can redirect every month. Here are places where people often find extra room:
- Pet supplies on autopilot. Compare the price of food and litter at two or three stores. Buying larger bags or using a store's subscribe-and-save option can lower the monthly cost. Move the difference into the pet fund.
- Subscriptions you forgot about. Look at your last two bank statements. Cancel one streaming service or app you have not used in a month.
- Grocery planning. Planning meals for the week and shopping with a list usually cuts impulse buys.
- Phone and internet plans. Call your provider and ask if there is a cheaper plan with the same features you actually use.
- Round-ups. Some banks let you round each card purchase up to the next dollar and move the change into savings. Point those round-ups at your pet fund.
Pick just one or two of these to start. A plan you can keep is better than a perfect plan you quit after three weeks.
What is the step-by-step plan to build the fund?
Follow these steps in order. The whole setup takes about an hour.
1. Open a separate savings account. Name it something like "Pet Emergency" in your banking app. Keeping it apart from your checking account makes it harder to spend by accident. Many online banks let you open one with no minimum balance. Check for monthly fees before you sign up.
2. Set an automatic transfer. Choose a fixed amount and schedule it for the day after payday. Even a small amount each paycheck adds up over a year.
3. Use a simple formula to choose the amount. Divide your target by the number of months you want to reach it. For example, if your target is $1,200 and you want to reach it in 12 months, you need $100 a month. If that is too much, stretch it to 18 or 24 months. Slower is fine.
4. Add windfalls. Tax refunds, a birthday check, money from selling something online: put part of it into the pet fund.
5. Check the balance once a month. Do it on the same day each month. If you had to use the fund, restart your transfers right away.
6. Raise the target as your pet ages. Older animals often need more care. Review your target once a year, around your pet's yearly checkup.
Is pet insurance worth it, or is saving enough?
This depends on your pet, your budget and the specific policy. Neither choice is right for everyone. Here is a simple way to compare:
| Question to ask | Why it matters |
|---|---|
| What is the monthly premium? | This is money you pay every month even if nothing happens. |
| What is the deductible? | You pay this amount first before the insurance pays anything. |
| What percentage does it pay back? | Many plans pay back only part of the bill after the deductible. |
| Is there a yearly or lifetime limit? | A low limit can leave you paying a big bill anyway. |
| What is excluded? | Pre-existing conditions are often not covered. Read this part carefully. |
| Do you pay first and wait for a refund? | Many plans work this way, so you still need cash on hand at the clinic. |
That last row is important. Even with insurance, you often have to pay the vet at the time of treatment and get money back later. So a pet fund is still useful. It covers the gap until the refund arrives.
Before you buy any policy, read the full terms, not just the sales page. If you are unsure whether a policy makes sense for your finances, a fee-only financial planner or a nonprofit credit counselor can help you look at the whole picture.
What if the emergency comes before the fund is ready?
Sometimes the emergency comes first. If that happens, stay calm and work through these steps:
1. Ask for a written estimate before treatment. Most clinics will give you one. Ask them to list what is urgent and what can wait.
2. Ask about treatment options. There is often more than one way to treat a problem. Ask, "Is there a less expensive option that is still safe for my pet?"
3. Ask about payment plans. Some clinics offer in-house plans. Others work with third-party financing companies.
4. Read financing terms very carefully. Some medical credit cards offer "no interest" for a few months, but if you do not pay the full amount by the deadline, you may be charged interest going back to the first day. Know the exact date and the exact amount before you sign.
5. Look for local help. Animal shelters, humane societies and some veterinary schools offer lower-cost care or know of assistance programs in your area.
6. Avoid payday loans. They usually come with very high fees and can create a bigger money problem than the vet bill.
After the emergency, do not let guilt stop you. Start or restart your pet fund the same week, even with a small amount.
How can you lower the odds of an emergency?
You cannot prevent every accident, but some habits reduce risk and, over time, cost:
- Keep up with yearly checkups and vaccines. Your vet can catch some problems early, when treatment is usually simpler.
- Pet-proof your home. Keep medicines, cleaning products, chocolate, grapes, onions, string and small toys out of reach. Ask your vet which foods and plants are dangerous for your type of pet.
- Use a leash and a secure yard. Many injuries happen when pets run loose.
- Keep your pet at a healthy weight. Extra weight can lead to joint and other health problems. Your vet can tell you the right weight for your pet.
- Save emergency numbers in your phone. Store your vet, the nearest 24-hour hospital and an animal poison control line. In an emergency, you will not want to search for them.
When in doubt about your pet's health, call your vet. Do not wait to see if a serious symptom goes away on its own just to save money. Waiting can make treatment harder and more expensive.
Your next step today
Before the day ends, do these three things:
1. Call your vet and the nearest emergency clinic and write down their emergency exam prices.
2. Open a separate savings account and name it "Pet Emergency."
3. Schedule an automatic transfer for the day after your next payday, even if it is small.
That is it. In under an hour, you will have moved from hoping nothing goes wrong to having a real plan when something does.
FAQ
How much should I keep in a pet emergency fund?
Base it on real prices from your vet and the nearest 24-hour clinic. For a young, insured pet, cover your deductible plus one emergency exam. For an uninsured or senior pet, aim for one to two typical emergency bills.
Do I still need savings if I have pet insurance?
Usually yes. Many plans make you pay the clinic first and refund you later, and you still pay the deductible and your share of the bill.
What if my pet has an emergency before my fund is ready?
Ask for a written estimate, ask about lower-cost treatment options and payment plans, read any financing terms carefully, and check local shelters or vet schools for help. Avoid payday loans.
Clear money tips in your inbox. No hype.
Educational content, not personalized financial advice. Sources cited where applicable.