Budget for a New Baby Without Cutting What Really Matters

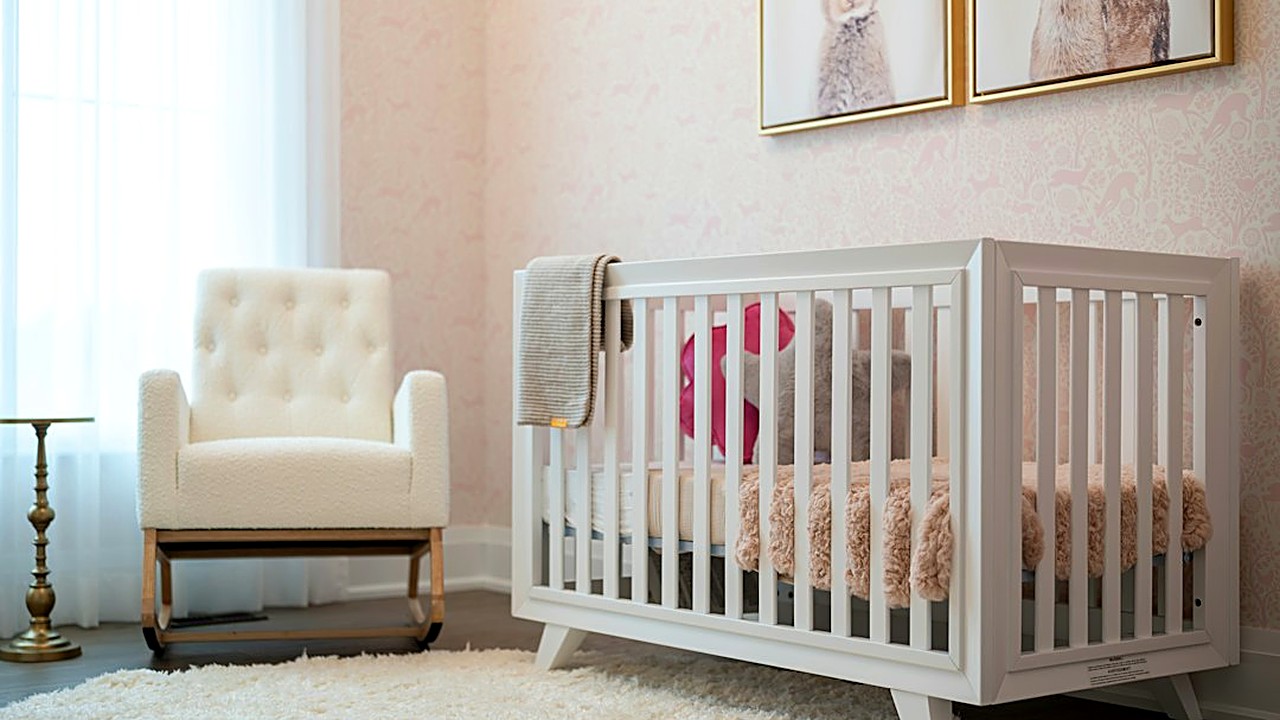
Quick answer: Protect your essentials first: housing, food, utilities, insurance and debt minimums. Add the baby's monthly costs as a new budget line, pay for it by trimming flexible spending, and save ahead for any income lost during parental leave.↗ Share on X
You can budget for a new baby without cutting essentials by doing three things in order: protect your fixed needs first (housing, food, utilities, insurance, debt minimums), add the baby's real monthly costs as their own budget line, and pay for that line by trimming flexible spending and planning around any drop in income during leave. The essentials stay. What changes is the order you pay things and where the extra money comes from. Start at least a few months before the due date if you can, because the biggest surprises are usually lost paychecks and medical bills, not diapers.
Below is a step-by-step plan, a sample budget, and a list of costs people often forget.
What counts as an "essential" that you should not cut?
 Pay for Your Pet's Yearly Vet Visit Without a Credit Card →
 How to Budget for Annual Fees Without Cashflow Pain →
 Hate Meal Planning? Cut Your Grocery Bill With 4 Habits →
Before you look for money, draw a line around what must stay paid every month. These are your essentials:
- Housing: rent or mortgage, plus property tax and insurance if they are not included.
- Utilities: electricity, water, heat, and a phone you need for work and the doctor.
- Food at home: groceries, not restaurants.
- Transportation to work and medical visits: car payment, insurance, gas, or transit pass.
- Health insurance premiums. This matters even more now.
- Minimum payments on debts. Missing them adds fees and hurts your credit.
- Child care, if you will need it when you go back to work.
Everything else is flexible. Streaming services, eating out, new clothes for adults, hobbies and extra shopping can shrink for a while without hurting your family's safety.
Clear money tips in your inbox. No hype.
Which new costs should you plan for?
Affiliate link. We may earn a commission on purchases, at no extra cost to you.
This content is informational and is not investment advice or financial consulting.
Baby costs come in two kinds: one-time purchases before birth, and monthly costs that keep going. Prices vary a lot by city, store and whether you buy new or used, so use this list to write your own numbers.
One-time costs (before or right after birth):
1. Car seat (buy new so you know its crash history)
2. Safe place to sleep: crib or bassinet with a firm, flat mattress
3. Stroller or baby carrier
4. Basic clothes in a few sizes
5. Bottles, if you plan to bottle feed or pump
6. Your share of hospital and delivery bills
Monthly costs (after birth):
1. Diapers and wipes
2. Formula, if you use it, or breast pump supplies
3. Extra laundry and household supplies
4. Higher health insurance premium after adding the baby
5. Doctor visit copays
6. Child care, if needed
To get your real numbers, check prices at two or three stores near you, and ask your health insurance company for the cost of adding a dependent and what you will owe for the birth.
How do you build the baby budget step by step?
 Utility Rates Keep Rising? Budget for Your Worst Month →
 How a Buffer Account Tames Your Variable Utility Bills →
 Night Shift Utility Budget: Plan for Bills You Pay by Day →
Use this process. It takes about one evening.
1. Write down your current take-home pay. Use what actually lands in your bank account, not your salary before taxes.
2. Write down what your income will be during leave. Ask your employer's HR office if your leave is paid, partly paid, or unpaid, and for how long. Check if your state offers paid family leave or disability pay for birth recovery.
3. List your essentials and their monthly cost. Use last month's bank statement.
4. Add the new baby line. Put your estimated monthly baby costs in one line called "Baby."
5. Subtract. Take-home pay minus essentials minus baby line. If the number is positive, that is your room for flexible spending and savings. If it is negative, go to step 6.
6. Cut flexible spending first. Go line by line through the non-essentials and decide what to pause, reduce or cancel.
7. Plan for the leave gap. Multiply the lost income per month by the number of months of reduced pay. That is the amount you need to save before the birth, or cover another way.
What does a sample baby budget look like?
The numbers below are only an example to show the method. Replace them with your own.
| Budget line | Before baby | After baby | Change |
|---|---|---|---|
| Housing | $1,400 | $1,400 | No change (essential) |
| Utilities and phone | $250 | $270 | Small increase (more laundry) |
| Groceries | $600 | $600 | No change (essential) |
| Transportation | $350 | $350 | No change (essential) |
| Health insurance | $200 | $320 | Increase (baby added) |
| Debt minimums | $150 | $150 | No change (essential) |
| Baby supplies | $0 | $200 | New line |
| Eating out | $250 | $60 | Cut |
| Streaming and apps | $60 | $20 | Cut |
| Shopping and extras | $300 | $100 | Cut |
| Savings | $200 | $290 | Kept, moved from cuts |
| Total | $3,760 | $3,760 | Same total |
Notice what happened: essentials did not move except where the baby made them go up. The money for diapers and the higher premium came from eating out, apps and shopping.
How do you cover the months of unpaid or reduced leave?
For many families, the hardest part is not the baby's costs. It is the drop in income while a parent is home. Plan this early.
1. Find out the exact leave terms. Ask HR in writing: how many weeks, how much pay, and when pay starts.
2. Calculate the gap. Example: if your paycheck drops by $1,200 a month for three months, the gap is $3,600.
3. Divide the gap by the months left before the due date. If you have six months, you need to set aside $600 a month. If that is too high, combine it with the next steps.
4. Pause extra debt payments (anything above the minimum) during the leave months, and restart after.
5. Ask about benefits you may not know about. Some employers offer short-term disability that covers part of birth recovery. Some states have paid family leave programs. Check your state's labor department website.
6. Check public programs if your income is limited. Programs like WIC can help with food and formula for eligible families, and Medicaid or CHIP may cover pregnancy and child health care. Eligibility depends on income and state rules, so apply and see.
Where can you save without cutting essentials?
These are real ways to spend less on the baby without giving up safety:
- Accept hand-me-downs and buy used for clothes, stroller, play mats and toys. Babies outgrow clothes fast.
- Do not buy a used car seat unless you know its full history, and never one past its expiration date or after a crash.
- Buy diapers in bulk once you know which size and brand fit, not before the birth.
- Use a gift registry for the bigger items and ask for practical gifts like diapers in larger sizes.
- Use your flexible spending account (FSA) or dependent care FSA if your employer offers one. These let you pay certain medical or child care costs with money that is not taxed.
- Ask the hospital for an itemized bill and a payment plan if the birth bill is large. Many hospitals also have financial assistance programs.
When should you talk to a professional?
A simple budget works for most families, but get help when:
- You have high-interest debt and cannot make the minimums with the new budget. A nonprofit credit counselor can help you build a plan.
- You are unsure what your health insurance covers for birth and newborn care. Call the insurer and ask for the details in writing.
- Your leave, disability or tax situation is complicated. A tax professional or your HR benefits team can explain your options, including new tax credits for which a child may make you eligible.
Every family's situation is different, and this article is general information, not personal financial advice.
Your next step
Tonight, open last month's bank statement and mark every charge as "essential" or "flexible." Then email your HR office one question: "How many weeks of leave will I have, and how much of my pay will I receive during that time?" With those two pieces of information, you can fill in the sample table above with your real numbers and know exactly how much you need to save each month before the baby arrives.
FAQ
How early should I start a baby budget?
As early as you can, ideally a few months before the due date. That gives you time to save for any income you lose during leave and to buy bigger items slowly.
What baby costs do people forget most?
The drop in income during leave, the higher health insurance premium after adding the baby, hospital bills, and child care when a parent goes back to work.
Is it safe to buy baby items used?
Clothes, strollers and toys are usually fine used. A car seat should only be used if you know its full history, it has never been in a crash, and it is not past its expiration date.
Clear money tips in your inbox. No hype.
Educational content, not personalized financial advice. Sources cited where applicable.