Total Loss Claim: How Insurers Calculate Your Payout
Quick answer: After declaring your car a total loss, the insurer pays you the vehicle's actual cash value (ACV) — what the car was worth the moment before the accident — minus your deductible. If you still owe money on the car, your lender gets paid first and you receive whatever is left. The offer is negotiable: you can challenge it with listings for comparable vehicles in your area.↗ Share on X
When your car is declared a total loss, the insurance company pays you its actual cash value (ACV) — what the vehicle was worth on the market the moment before the crash — minus your deductible. If the car still has a loan or lease on it, the lender is paid first from that amount, and you receive only what remains. The whole process typically runs through five steps: inspection, the total loss decision, the valuation report, the settlement offer, and the transfer of the title to the insurer. Each step has a point where you can push back, and the valuation step is where pushing back most often changes the number. Here is how the money actually flows, in order.
When does a car become a total loss?
 9 Things Car Insurers Check Besides Your Driving Record →
 Term Life Length: Match It to Your Youngest Child's Age →
 Auto Insurance Declarations Page: Decode It Line by Line →
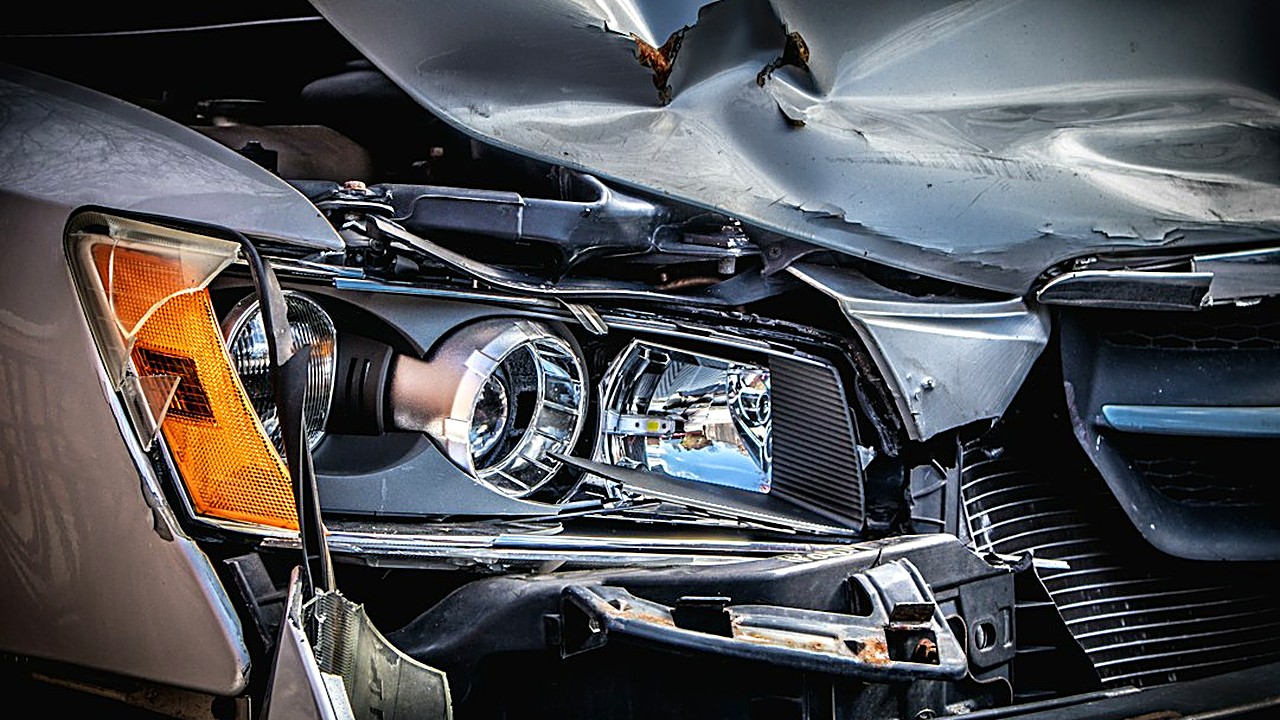
A car is 'totaled' when fixing it costs more than the insurer is willing to pay relative to its value. Two things decide that:
- The repair math. If estimated repairs plus the car's salvage value approach or exceed its pre-accident value, repairing makes no financial sense for the insurer.
- State thresholds. Many states set a total loss threshold — a percentage of the car's value (commonly somewhere between 60% and 100%, varying by state) above which the car must be declared a total loss. Other states use the repair-plus-salvage formula instead. Your state's insurance department website lists the rule that applies to you.
This is why a 12-year-old sedan gets totaled over a dented quarter panel while a newer SUV with worse damage gets repaired: the decision is about the ratio, not the damage.
Clear money tips in your inbox. No hype.
What exactly is actual cash value, and how is it set?
Affiliate link. We may earn a commission on purchases, at no extra cost to you.
This content is informational and is not investment advice or financial consulting.
Actual cash value is the market price of your exact car — same year, trim, mileage, options, and condition — in your local area, the day before the accident. It is not what you paid for the car, not what you owe on it, and not what a new replacement costs.
In practice, the insurer orders a valuation report from a third-party vendor. The report pulls recent sale prices of comparable vehicles near you and adjusts them for your car's mileage and condition. You have the right to a copy of this report. Ask for it — this document is the entire basis of your money, and errors in it are common enough to be worth checking:
1. Wrong trim level (a base model used as a comparable for your higher trim).
2. Mileage recorded incorrectly.
3. Missing options — tow package, premium audio, new tires you bought two months ago.
4. Condition rated 'fair' with no explanation when your maintenance records say otherwise.
Each of those errors moves the payout, and each can be corrected with evidence: photos, service records, receipts.
What gets added to and subtracted from the check?
 Car Insurance After a Lapse: How Insurers Price Your Risk →
 Will One Claim Raise Your Insurance Rates? What Changes →
 Premiums vs. Out-of-Pocket Costs: What You Actually Pay →
The settlement is not just the ACV number. A typical breakdown looks like this:
| Item | Effect on your payout |
|---|---|
| Actual cash value (ACV) | The starting number |
| Sales tax and transfer/registration fees | Added in many states, since replacing the car means paying tax again — ask if your state requires it |
| Your deductible | Subtracted, if the claim runs through your own collision coverage |
| Loan or lease balance | Paid directly to the lender first; you get the remainder |
| Salvage value | Subtracted only if you choose to keep the wrecked car |
Two of these surprise people constantly. First, the deductible applies even on a total loss — a $9,000 ACV with a $1,000 deductible pays $8,000 (if another driver was at fault and you claim against their insurer instead, no deductible applies). Second, the lender gets paid before you do. The insurer sends the payoff to the bank, and your check is the difference.
What if you owe more than the car is worth?
This is the painful scenario: the ACV comes in at $14,000 but your loan balance is $17,000. The insurer pays the lender $14,000 — and you still legally owe the remaining $3,000 on a car that no longer exists.
This gap is exactly what GAP coverage (gap insurance, sold with many car loans) exists for: if you bought it with the car loan or added it to your policy, it pays the difference between the ACV and the loan balance. If you are not sure whether you have it, check your loan paperwork and your policy declarations page before you accept any settlement, and tell the adjuster — the GAP claim is usually filed separately with the GAP provider.
If you do not have GAP coverage and are left with a balance, call the lender before missing any payment. Lenders deal with this situation routinely and may restructure the remainder. Ignoring it damages your credit over a car you cannot drive.
The five steps of the payout, in order
1. Inspection (first days). An adjuster or an appointed shop examines the car and writes a repair estimate.
2. Total loss declaration. The insurer runs the threshold math and notifies you the car is a total loss. From this point, stop any storage fees from piling up — move the car where the insurer directs, because storage charges can be deducted from settlements when delays are on your side.
3. Valuation report and offer. You receive the ACV figure, usually within one to two weeks of the declaration. Request the full valuation report immediately.
4. Negotiation or acceptance. You accept, or you counter with evidence (more on that below). Nothing obligates you to accept the first number.
5. Paperwork and payment. You sign the title over to the insurer, remove the plates and your belongings, and cancel or transfer the registration. Payment to the lender and to you typically follows within days of the signed paperwork. Keep your insurance active until the settlement closes — do not cancel the policy early.
The full timeline, start to finish, commonly runs two to six weeks, longer if liability is disputed or the title has issues.
How do you challenge a low offer?
You negotiate with comparables, not with feelings. The script is simple:
1. Pull 3 to 5 current listings for the same year, make, model, trim, and similar mileage, within your region. Dealer and marketplace listings both work; save them as PDFs or screenshots with dates visible.
2. Check the valuation report for the errors listed earlier — wrong trim, missing options, bad mileage.
3. Send the adjuster a short written counter: the corrected facts, your comparables, and the number they support. Writing beats phone calls because it creates a record.
4. If the insurer will not move and the gap is large, your policy may include an appraisal clause — each side hires an appraiser and a neutral umpire resolves the difference. For smaller disputes, a complaint to your state insurance department is free and gets claims reviewed.
If the claim involves injuries, a dispute over who was at fault, or a settlement gap worth serious money, talk to a licensed professional — a public adjuster or an attorney who handles insurance claims — before signing anything. A signed release generally ends the claim for good, so get advice before you sign, not after.
Can you keep the car after a total loss?
Usually yes — it is called owner retention. The insurer pays you the ACV minus the deductible minus the car's salvage value, and the car stays with you, but with a salvage title in most states. Think twice: a salvage title cuts resale value sharply, some insurers will not fully cover a rebuilt car, and the repairs that the insurer judged uneconomical still cost real money. Keeping the car mostly makes sense for mechanically minded owners, low-value cars with cosmetic damage, or sentimental vehicles you intend to keep forever.
Your next practical step
If you are in a total loss claim right now, do two things today: request the complete valuation report from your adjuster in writing, and pull your loan payoff amount from your lender. With those two numbers side by side, you will know exactly where you stand — whether the offer is fair, whether a gap exists, and whether it is worth countering with comparables before you sign the release.
FAQ
Do I still pay my deductible if the car is a total loss?
Yes, if the claim goes through your own collision or comprehensive coverage — the deductible is subtracted from the settlement check. If another driver was at fault and you claim against their liability insurance instead, no deductible applies. Some insurers also recover your deductible for you later through subrogation if the other driver was at fault.
How long does a total loss payout take?
Commonly two to six weeks from the accident: a few days for inspection, one to two weeks for the valuation and offer, then days for paperwork and payment after you sign. Disputed fault, missing title documents, or negotiation extend the timeline. You can shorten your part by sending documents promptly and requesting the valuation report early.
What happens to my insurance policy after the car is totaled?
Keep the policy active until the settlement is fully paid — canceling early can complicate the claim. Afterward, you can transfer the policy to your replacement vehicle, usually keeping your rates and history. You may also be owed a refund of unused premium on the totaled car if you prepaid.
Clear money tips in your inbox. No hype.
Educational content, not personalized financial advice. Sources cited where applicable.